QUESTION PAPER
2023 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2023 — Set 3
2023
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2023
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 46 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 27 are multiple choice questions
- Section B – questions number 28 to 35 are short answer
- Section C – questions number 36 to 39 are long answer type i
- Section D – questions number 40 to 46 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
‘The business of a partnership concern may be carried on by all the partners, or any of them acting for all’ The above statement highlights which of the following features of partnership ?
After doing the adjustments regarding drawings Rs 40,000, share of profit Rs 24,000 and the additional capital introduced Rs 32,000, the capital of Ashok, a partner, as on 31.03.2022 was Rs 5,00,000. His capital as on 01.04.2021 was:
Josh and Jeevan were partners in a firm. During the year ended 31.03.2022 Jeevan withdrew Rs 5,000 per month starting from 30.06.2021. The partnership deed provided that interest on drawings will
be charged @ 12% per annum. The average number of months for which interest on Jeevan’s total drawings will be charged is :
X and Z were partners in a firm with capitals of Rs 45,000 each. They admitted Y as a new partner for 1/3 rd share in the profits of the firm. Y brought Rs 60,000 as his capital. Based on Y’s share in the profits of the firm and his capital contribution, the goodwill of the firm will be :
C, D and E were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. They admitted F as a new partner for 1/4 share in the profits which was sacrificed by C, D and E in the ratio of 2 : 1: 2. C’s new share in the profits will be :
K.C. Ltd. took over office furniture of Rs 90,000, office equipment of Rs 1,80,000 from J.C. Ltd. and its liabilities of Rs 20,000 for a purchase consideration of Rs 3,60,000. The payment to J.C. Ltd.
was made by issue of 9% debentures of Rs 50 each at a discount of 10%. The amount to be debited to ‘Discount on Issue of Debentures Account’ will be :
Raja Ltd. purchased machinery for Rs 25,00,000 from Sharma Ltd. The payment to Sharma Ltd. was made by issue of equity shares of Rs 10 each at a premium of 25%. The amount to be credited to the
‘Securities Premium Reserve Account’ on issue of equity shares will be
Assertion (A) : Interest on bearer debentures is paid to a person who produces the interest coupon attached to such debentures.
Reason (R): Bearer debentures are debentures which can be transferred by way of delivery and the company does not keep any record of the debenture holders.
On the dissolution of a partnership firm there existed a balance of Rs 45,000 in Sundry Debtors Account and a balance of Rs 8,000 in Provision for Bad Debts Account in the books of the firm. The amount by
which ‘Realisation Account’ will be debited for closing Sundry Debtors Account will be :
S and T were partners in a firm sharing profits and losses in the ratio of 3 : 2. They admitted U as a new partner in the firm. On U’s admission there existed a provision for bad and doubtful debts of Rs 7,000. It was decided to write off Rs 3,000 as bad debts. The remaining debtors were considered as good. The amount to be debited/credited to Revaluation Account on account of the above treatment will be :
C and D were partners in a firm. E was admitted as a new partner for 1 / 6 share. E acquired 1 / 3 rd of his share from C and the remaining from D.
The sacrificing ratio of C and D was :
A, B and C were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. With effect from 01.04.2023, they agreed to share profits and losses equally. Due to change in the profit
sharing ratio, B’s gain or sacrifice will be :
A and B were partners in a firm. They admitted C as a new partner for 1/3 rd share in the profits of the firm which he acquired
from A. A’s new share in the profit will be :
P, Q and R were partners in a firm. On 31.03.2022, R died. R’s share was taken over by P. P’s new share in the profits of the firm will be :
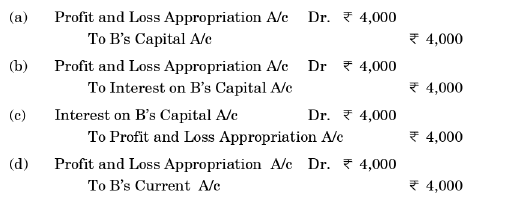
B and D were partners. According to the provisions of partnership deed, interest on B’s capital for the year ended 31.03.2022 was calculated at Rs 4,000.
The necessary journal entry for transferring interest on B’s capital to Profit and Loss Appropriation Account will be
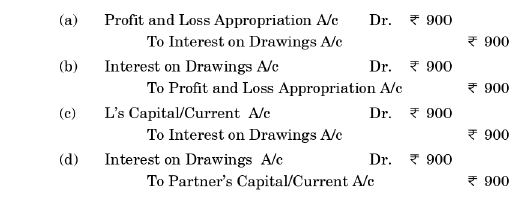
K and L were partners in a firm. Their partnership deed provided that interest on partner’s drawings will be charged @ 12% per annum. Interest on L’s drawings for the year ended 31.03.2022 was calculated at Rs 900.
The necessary journal entry for charging interest on L’s drawings will be :
In which of the following conditions is a partnership firm dissolved by ‘Agreement’ ?
On 1st April, 2022, Zaira Ltd. issued 5000, 8% Debentures of Rs 100 each at 5% premium, redeemable at a premium of 10% after 3 years. ‘Loss on Issue of Debentures Account’ will be debited by which of the following amount ?
On 1st April, 2022, Zaira Ltd. issued 5000, 8% Debentures of Rs 100 each at 5% premium, redeemable at a premium of 10% after 3 years.
The total interest due on debentures for the year ending 315t March, 2023 will be :
BB Ltd. forfeited 4000 shares of Rs 10 each for non-payment of final call of Rs 5 per share. The forfeited amount was Rs 20,000. The minimum amount per share at which these shares can be re-issued will be :
If the Operating Ratio of Pathway Ltd. is 30%, its Operating Profit Ratio will be :
Which of the following are known as Efficiency Ratios ?
Which of the following are included in ‘Cash’ for the purpose of preparing Cash Flow Statement ? (i) Cash in hand (ii) Marketable securities (iii) Demand deposits with banks (iv) Trade receivables Choose the correct option from the following :
Section B
P and Q were partners in a firm sharing profits and losses in the ratio of 2: 1. On 01.04.2022, they admitted R as a new partner for 1/10 th share of profits with a guaranteed minimum of Rs 50,000. P and Q continued to share profits as before but agreed to share any deficiency on account of
guarantee to R in the ratio of 3 : 2. The net profit of the firm for the year ended 31.03.2023 was Rs 3,00,000.
Pass necessary journal entries in the books of P and Q for the above transactions.
Nisha, Priya and Rajat were partners in a firm sharing profits in the ratio of 2 : 2 : 1. The firm closes its books on 31st March every year. Priya died on 15t July 2022. On Priya’s death, the goodwill of
the firm was valued at Rs 3,00,000 and her share in the profits of the firm till the time of her death was to be calculated on the basis of previous year’s profit which was Rs 6,00,000.
Pass necessary journal entries for the treatment of goodwill and Priya’s share of profit at the time of her death.
Sharma and Verma were partners in a firm sharing profits and losses in the ratio of 3 : 2. Their fixed capitals were Rs 14,00,000 and Rs 10,00,000 respectively. The partnership deed provided for
the following :
(i) Interest on capital @ 10% per annum.
(ii) Interest on drawings @ 12% per annum.
During the year ended 31.03.2023, Sharma withdrew Rs 2,00,000 and Verma withdrew Rs 1,00,000. After preparing the accounts for the year ended 31.03.2023, it was realised that interest on capital
was not allowed and interest on drawings was not charged.
Showing your working notes clearly pass necessary journal entries in the books of the firm to rectify the above error.
On 01.04.2021, Aman Ltd. purchased from Kamal Ltd. Machinery Rs 5,00,000, Furniture ¥ 3,00,000 and Land and Building Rs 40,00,000. It also took over the sundry creditors of Kamal Ltd. of
Rs 8,00,000. The purchase consideration was Rs 36,00,000. Payment to Kamal Ltd. was made by issue of 9% Debentures of Rs 100 each at a discount of 10%. On 31.03.2022, the company decided to write off ‘Discount on Issue of Debentures Account’ according to the
provisions of Companies Act, 2013.
Pass necessary journal entries for the above transactions in the books of Aman Ltd.
On 01.04.2021, Bain Ltd. purchased from Cayres Ltd., Machinery at RS 17,00,000 and Land and Building at Rs 40,00,000. It also took over its liabilities amounting to Rs 7,00,000. The purchase
consideration of Rs 60,00,000 was paid as follows : Rs 5,00,000 through a cheque and the balance by issue of 9% debentures of Rs 100 each at a premium of 10%.
Pass necessary journal entries for the above transactions in the books of Bain Ltd.
On 01.04.2022, Ravi, Kavi and Avi started a partnership firm with fixed capitals of Rs 6,00,000, Rs 6,00,000 and Rs 3,00,000 respectively. The partnership deed provided for the following :
(i) Interest on capital @ 10% per annum.
(ii) Interest on drawings @ 12% per annum.
(iii) An annual salary of Rs 1,20,000 to Avi.
(iv) Profits and losses were to be shared in the ratio of their capitals.
The net profit of the firm for the year ended 31.03.2023 was Rs 3,08,000. Interest on partners’ drawings was Ravi Rs 4,800, Kavi Rs 4,200 and Avi Rs 3,000.
Prepare Profit and Loss Appropriation Account of Ravi, Kavi and Avi for the year ended 31.03.2023.
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of a company as per Schedule III, Part I of the Companies Act, 2013 :
(a) Computer Software
(b) Work-in-Progress
(c) Calls in Advance
These ratios are calculated to determine the ability of the business to service its debt in the long run. Identify and state the significance of three such ratios.
Section C
A, B and C were partners in a firm sharing profits and losses in the ratio of 7:1:2. From 01.04.2022 they decided to share the profits in the ratio of 5 : 3 : 2. For this purpose the goodwill of the firm was valued at
Rs 3,60,000. Revaluation of assets and reassessment of liabilities resulted in a loss of Rs 50,000.
Calculate share of gain of loss of the individual partners on change in profit sharing ratio and pass necessary journal entries for the above in the books of the firm.
MM Ltd. is registered with an authorised share capital of Rs 10,00,00,000 was divided into 1,00,00,000 equity shares of Rs 10 each. The company invited applications for issuing 10,00,000 equity shares. The amount per share was payable as follows :
On Application - Rs 3 per share
On Allotment - Rs 4 per share
On First and Final Call - Rs 3 per share
The issue was fully subscribed. All calls were made and were duly received except the first and final call on 1000 shares.
Present the share capital in the Balance Sheet of the company as per the provisions of Schedule III Part I of the Companies Act, 2013 and also prepare ‘Notes of Accounts’.
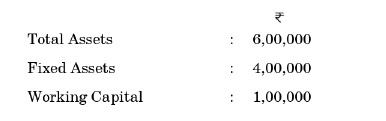
Calculate Current Ratio from the following information :
Average inventory of Beeta Ltd. was Rs 80,000. Its inventory turnover ratio was 4 times. It sells goods at a profit of 20% on revenue from operations. Calculate its ‘Revenue from Operations’.
Section D
Pass necessary journal entries for the issue of debentures in the following cases
(i) Issued 1000, 9% debentures of Rs 100 each at a premium of 10%, redeemable at a premium of Rs 15 per debenture.
(ii) Issued Rs 2,00,000, 9% debentures of Rs 100 each at 6% discount, redeemable at 5% premium.
(iii) Issued 3500, 9% debentures of Rs 100 each at par, redeemable at a premium of 20%.
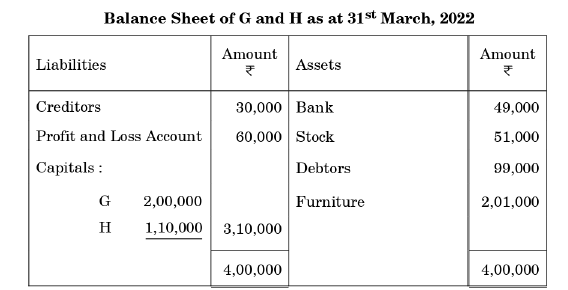
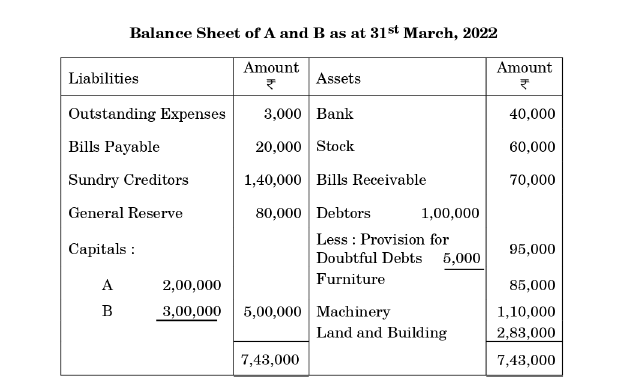
G and H were partners in a firm sharing profits and losses in the ratio of 3:1. 0On 31.03.2022, their Balance Sheet was as follows :
On the above date, the firm was dissolved. Debtors realised Rs 1,10,000 and furniture realised Rs 70,000. Stock was taken over by G at Rs 71,000. Creditors were paid 10% less. Expenses on dissolution amounted to Rs 20,000.
Prepare Realisation Account and Partners’ Capital Accounts.
CCL Ltd. invited applications for issuing 75,000 equity shares of Rs 10 each at a premium of Rs 3 per share.
The amount was payable as follows :
On Application — Rs 2 per share
On Allotment — Rs 6 per share (including premium)
Second and Final Call — Balance
Applications for 1,20,000 shares were received. Application for 45,000 shares were rejected and the excess application money was refunded. Full allotment was made to remaining applicants. All
moneys due were received except for Harish, a shareholder holding 2000 shares, who failed to pay the first and second and final call money.
Pass necessary journal entries for the above transactions in the books of the company.
Pass necessary journal entries for the forfeiture and reissue of shares in the following cases:
(i) CC Ltd. forfeited 10,000 shares of Rs 10 each, Rs 8 called up, for non-payment of allotment money of Rs 3 per share and first call of Rs 3 per share. Out of these, 2000 shares were
reissued for Rs 7 per share, Rs 8 paid up.
(ii) GG Ltd. forfeited 2000 shares of Rs 10 each fully called up, issued at a premium of 10% on which only application money of Rs 3 per share was received. Out of these, 500 shares were re-issued at Rs 11 per share, fully paid up.
A and B were partners in a firm sharing profits and losses in the ratio of 3 : 1. On 31.03.2022, their Balance Sheet was as follows :
On the above date, C was admitted as a new partner for 1/5 share in the profits on the following terms :
(i) C will bring Rs 2,00,000 as her capital and Rs 1,60,000 as her share of goodwill premium.
(ii) Stock will be appreciated by Rs 1,500.
(iii) Stock will be appreciated by Rs 1,500. Debtors of Rs 5,000 will be written off as bad debts and a
provision of 10% for bad and doubtful debts will be maintained.
Prepare Revaluation Account and Partners’ Capital Accounts.
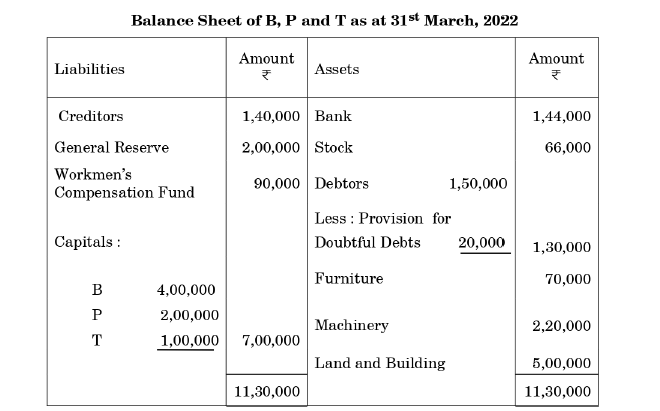
B, P and T were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. On 31.03.2022, their Balance Sheet was as follows :
On the above date, B retired from the firm on the following terms :
(i) Goodwill of the firm will be valued at Rs 3,60,000 and B’s share will be adjusted without opening goodwill account.
(ii) Furniture will be reduced to Rs 60,000.
(iii)) A claim of Rs 1,00,000 was admitted for workmen’s compensation.
(iv) B was paid Rs 20,000 through a cheque and the balance was transferred to his loan account.
Prepare Revaluation Account and Partners’ Capital Accounts.
Read the following hypothetical text and answer the given questions on
this basis :
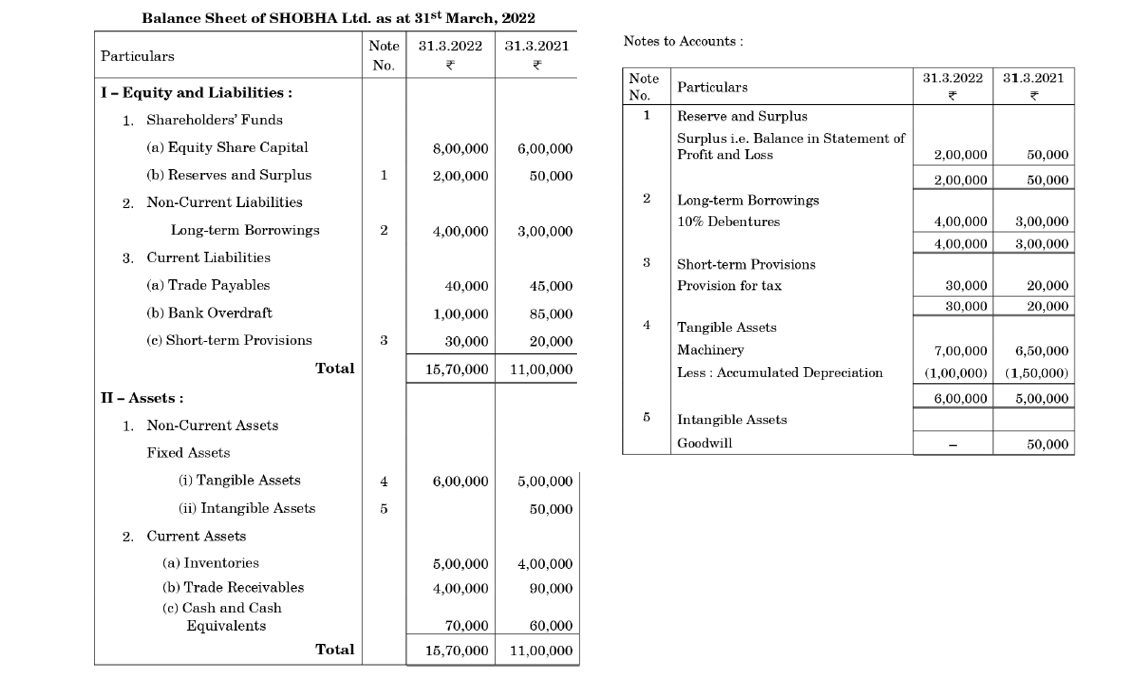
Shobha started a small enterprise selling hand-knitted sweaters under ‘Skill India Scheme’. As the business grew, the revenue started increasing. On 1st April 2020, she decided to form ‘Shobha Ltd.’ along with twelve other like-minded persons. The Balance Sheet of Shobha Ltd. as at 31st March, 2022, is given below
From the figures given in the Balance Sheet and additional information, calculate ‘Cash Flows from Investing Activities’ and ‘Cash Flows from Financing Activities
Additional Information :
(i) A piece of machinery costing Rs 1,60,000 was sold at a loss of Rs 20,000. Depreciation charged during the year amounted to Rs 40,000.
(ii) Rs 1,00,000, 10% debentures were issued on 31.3.2022.
Paper Details
CBSE Board Exam 2023
Class
Class 12 Commerce
Subject
Accountancy
Year
2023
Set
Set 3
Other Years — Accountancy