QUESTION PAPER
2024 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2024 — Set 3
2024
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2024
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 46 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 27 are multiple choice questions
- Section B – questions number 28 to 35 are short answer
- Section C – questions number 36 to 39 are long answer type i
- Section D – questions number 40 to 46 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
Anu, Bina and Roy were partners in a firm sharing profits and losses in the ratio of 3 : 2 : 1. Roy retired and his share was acquired by Anu. The new profit sharing ratio between Anu and Bina after Roy’s retirement will be :
Asha, Yug and Zubin were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 2. Zubin retired. Zubin’s share was acquired equally by Asha and Yug. The new profit sharing ratio between Asha and Yug after Zubin’s retirement was :
Nagar Ltd. issued 6,000, 11% Debentures of ₹ 100 each at a discount of 10% redeemable at a premium. ‘Discount on issue of debentures’ and ‘Premium on redemption of debentures’ were accounted for through ‘Loss on issue of debentures account’. If the amount of ‘Loss on issue of debentures’ was ₹ 90,000, then the amount of premium on redemption of debentures was :
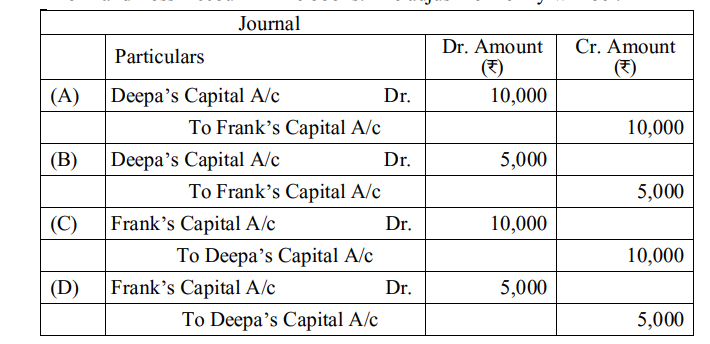
Deepa, Elton and Frank were partners in a firm sharing profits in the ratio of 2 : 2 : 1. With effect from 1st April, 2023 they decided to change their profit sharing ratio as 1 : 2 : 2. There existed a Debit Balance of Profit and Loss Account of ₹50,000 in the books of the firm on the date of change in profit sharing ratio. The partners decided to retain the Debit Balance of Profit and Loss Account in the books. The adjustment entry will be :
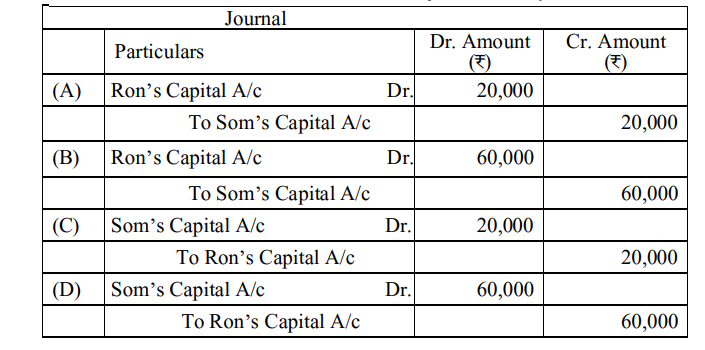
Som, Pam and Ron were partners in a firm sharing profits in the ratio of 7 : 2 : 1. With effect from 1st April, 2023 they decided to change their profit sharing ratio to 1 : 2 : 7. There existed a Credit Balance in the Profit and Loss Account of ₹ 1,00,000 on the date of change in profit sharing ratio in the books of the firm. The partners decided to retain the Credit Balance in Profit and Loss Account in the books. The adjustment entry will be :
Sinoy Ltd. issued 20,000 shares of ₹ 10 each at a premium of ₹6. The amount was payable as follows : On Application – ₹ 7 per share(Including Premium ₹ 1 per share) On Allotment – ₹ 5 per share (Including Premium ₹ 2 per share) On First and Final call – Balance The issue was fully subscribed. All the money was duly received except the allotment and first and final call on 1,000 shares. These shares were forfeited. On forfeiture of these shares, the ‘Securities Premium Account’ will be debited by :
Daksh and Ekansh are partners in a firm sharing profits and losses in the ratio of 3 : 1. Their capitals were ₹ 1,60,000 and ₹ 1,00,000 respectively. As per partnership deed, they were entitled to interest on capital @ 10% p.a.. The firm earned a profit of ₹ 13,000 for the year ended 31st March, 2023.
Daksh’s interest on capital will be :
Daksh and Ekansh are partners in a firm sharing profits and losses in the ratio of 3 : 1. Their capitals were ₹ 1,60,000 and ₹ 1,00,000 respectively. As per partnership deed, they were entitled to interest on capital @ 10% p.a.. The firm earned a profit of ₹ 13,000 for the year ended 31st March, 2023. Ekansh’s share of profit/loss will be :
Arjun, Babita and Charlie were partners in a firm sharing profits in the ratio of 2 : 2 : 1. They admitted Dheeraj for 5 1 th share in the profits of the firm. He has to contribute proportionate capital to acquire 5 1 th share in future profits. On the date of admission, the capitals after all adjustments relating to goodwill and revaluation of assets and liabilities, were : Arjun ₹ 62,000, Babita ₹52,000 and Charlie ₹36,000. The capital brought by Dheeraj will be :
Nikhil and Sharat were partners in a firm sharing profits and losses in the ratio of 4 : 3. Nikhil withdrew ₹ 6,000 on the first day of every quarter for the year ended 31st March, 2023. Interest on drawings is to be charged @ 5% p.a. Interest on Nikhil’s drawings will be calculated for :
Pawan, Kavita and Gaurav were partners in a firm. The firm was dissolved. Creditors took over furniture of book value of ₹ 60,000 at 10% less than the book value in part settlement of their amount of ₹ 60,000. The balance amount was paid to them through cheque. The amount paid through cheque will be :
Renu, Trilok and Mansi were partners in a firm sharing profits and losses in the ratio of 9 : 6 : 5. Hina was admitted as a partner for 1 / 10 th share in the profits which she acquired equally from Renu and Trilok. The new profit sharing ratio after Hina’s admission will be :
Ashu and Ria were partners in a firm sharing profits and losses in the ratio of 4 : 3. They admitted Nitu for a 3 / 7 th share in the profits of the firm, which she took 2 / 7 th from Ashu and 1 / 7th from Ria. The new profit sharing ratio between Ashu, Ria and Nitu will be :
There are two statements Assertion (A) and Reason (R) : Assertion (A) : The maximum number of partners in a partnership firm are 50. Reason (R) : The maximum number of partners are prescribed by the Partnership Act, 1932. Choose the correct option from the following :
Beeta Ltd. offered for subscription 1,00,000 equity shares of ₹ 10 each at a premium of 100% payable entirely on application. Applications were received for 5,00,000 equity shares. The company decided to allot the shares on pro-rata basis to all the applicants. The amount received by the company on application was :
The amount of share capital which a company is authorised to issue by its Memorandum of Association is called :
Sale of patents of ₹50,00,000 will result in :
The Quick Ratio of a company is 1 : 1. Which of the following transactions will result in increase of this ratio ?
Which of the following is not a limitation of ‘Analysis of Financial Statements’ ?
Ratios that are calculated for measuring the efficiency of operations of business based on effective utilisation of resources are known as :
Section B
Falak, Girdhar and Hemang were partners in a firm sharing profits and losses in the ratio of 6 : 3 : 1. Girdhar retired. Falak and Hemang decided to share profits in future in the ratio of 3 : 2. On the day of Girdhar’s retirement, goodwill of the firm was valued at ₹ 1,00,000.
Calculate gaining ratio and pass necessary journal entry to record the treatment of goodwill on Girdhar’s retirement.
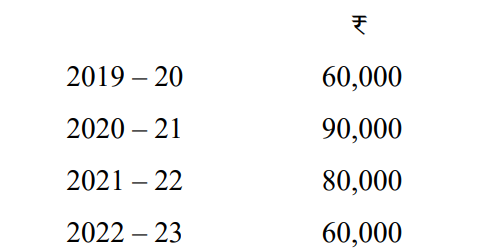
Piyush and Rishabh were partners in a firm with a combined capital of ₹ 4,00,000. The normal rate of return was 15%. The profits of the last four years were :
The closing stock for the year 2022 – 23 was undervalued by ₹ 10,000. Calculate goodwill of the firm based on capitalisation of average profit.
Sheetal Ltd. purchased building worth ₹ 2,0,000, plant and machinery worth ₹ 2,00,000, furniture worth ₹ 40,000 and took over liabilities of ₹ 30,000 from Poonam Ltd. for a purchase consideration of ₹4,40,000. The purchase consideration was paid by issuing 12% Debentures of ₹ 100 each at a premium of 10%
Pass the necessary journal entries in books of Sheetal Ltd. to record the above transactions.
On 1st April, 2023, Simple Ltd. took over assets of ₹ ,00,000 and liabilities of ₹ 1,00,000 from Temur Ltd. at an agreed value of ₹ 16,00,000. Simple Ltd. paid the amount to Temur Ltd. as follows :
(i) Issued a bank draft of ₹ 1,00,000.
(ii) Issued 8% Debentures of ₹ 100 each at a premium of 50% in satisfaction of the balance amount of purchase consideration.
Pass the necessary journal entries in the books of Simple Ltd. to record the above transactions.
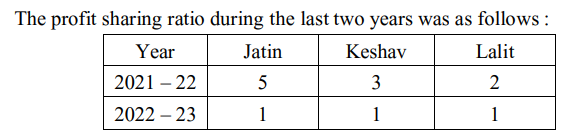
Jatin, Keshav and Lalit were partners in a firm with fixed capitals of ₹ 1,20,000, ₹ 1,00,000 and ₹ 80,000 respectively. As per the partnership deed, there was a provision for allowing interest on capitals @ 10% p.a., but entries for the same had not been made for the last two years.
Pass an adjustment entry of the beginning of the third year, i.e., on 1st April, 2023.
Meera, Neena and Ojas were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. The partnership deed provided for charging interest on drawings @ 10% p.a. The drawings of Meera, Neena and Ojas during the year ended 31st March, 2023 amounted to ₹60,000, ₹0,000 and ₹ 40,000 respectively. After the final accounts had been prepared, it was discovered that interest on drawings had not been taking into consideration.
Pass the necessary adjustment entry.
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of the company as per Schedule III, Part I of the Companies Act, 2013
(a) Bank Balance
(b) Public Deposits
(c) Bank Overdraft
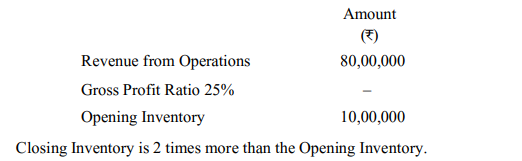
From the following information, calculate Inventory Turnover Ratio :
Section C
Shringar Ltd. was registered with an authorised capital of ₹ 5,00,000 divided into equity shares of ₹ 10 each. The company issued a prospectus inviting applications for 20,000 equity shares. The amount was payable as follows :
On Application – ₹ 3 per share
On Allotment – ₹ 5 per share
On First and Final call – Balance
Applications were received for 19,000 equity shares and allotment was made to all the applicants. All the amounts were duly received except the first and final call on 5,000 shares.
Present the share capital in the Company’s Balance Sheet as per Schedule III, Part I of Companies Act, 2013. Also prepare ‘Notes to Accounts’ for the same.
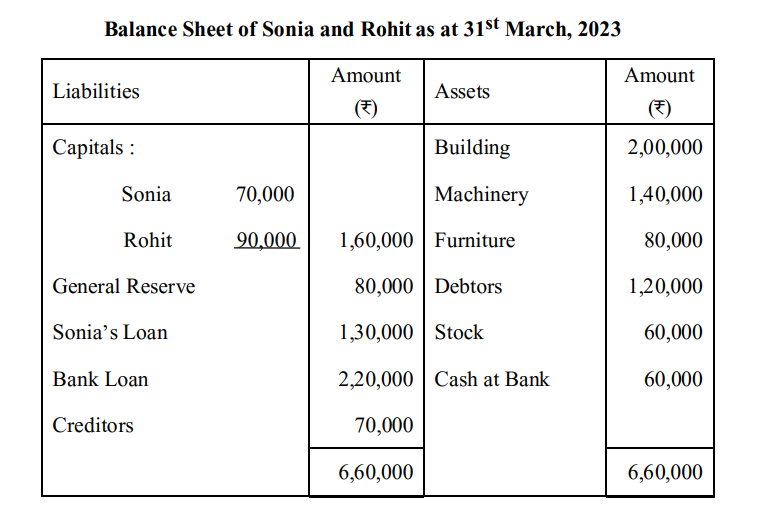
Sonia and Rohit were partners in a firm sharing profits and losses in the ratio of 3 : 2. On 31st March, 2023 their Balance Sheet was as follows :
The firm was dissolved on the above date on the following terms :
(i) Building, machinery and furniture realised ₹ 3,44,000.
(ii) Debtors realised 90% only.
(iii) Creditors took away half of the stock in full settlement of their account.
(iv) Remaining stock realised ₹ 72,000.
(v) Realisation expenses amounting to ₹14,000 were paid by Rohit.
Prepare Realisation Account
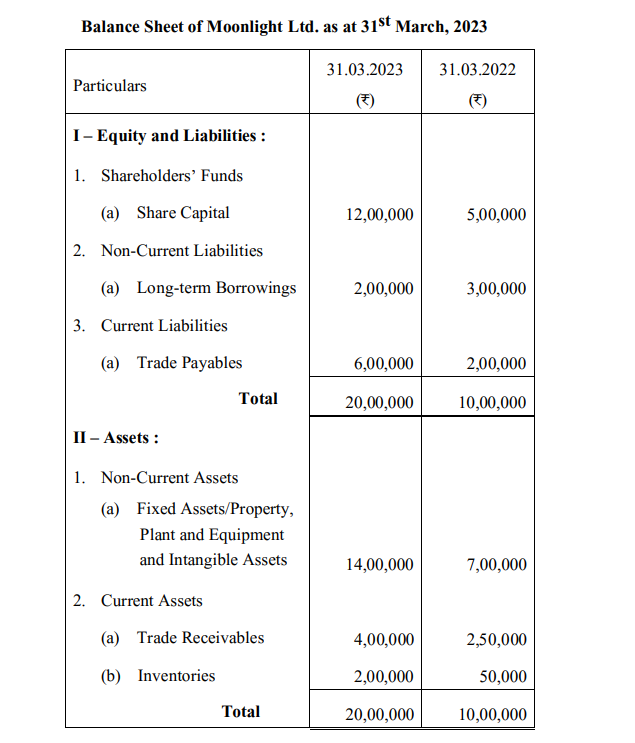
From the given Balance Sheet of Moonlight Ltd., prepare a Common Size Balance Sheet :
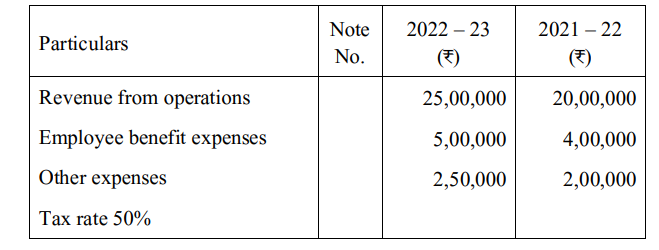
From the following particulars of Accent Ltd., prepare a Comparative Statement of Profit and Loss for the year ended 31st March, 2023 :
Section D
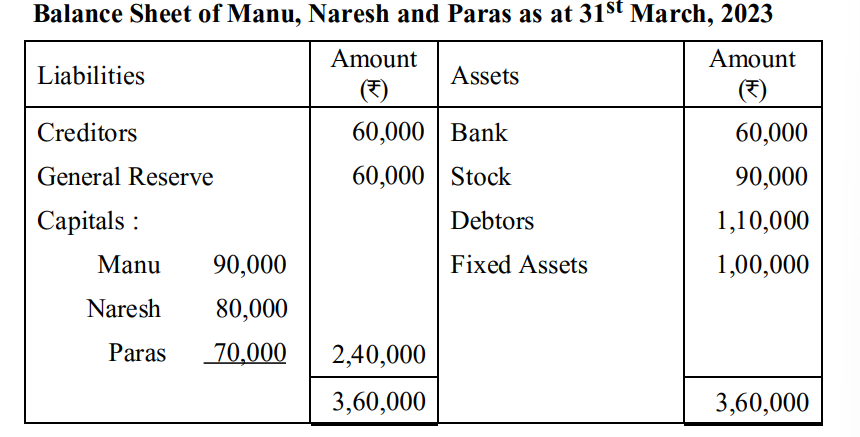
Manu, Naresh and Paras were partners in a firm sharing profits and losses equally. Their Balance Sheet as at 31st March, 2023 was as follows :
Paras died on 31st January, 2024. It was agreed between his executors and remaining partners that
(i) Goodwill be valued at ₹ 30,000 at 3 years purchase of average profits of the previous three years.
(ii) Share of profit up to the date of death on the basis of average profits of the previous three years. Paras’s share of profit amounted to ₹ 48,000.
(iii) Interest on capital is to be provided @ 12% p.a
(iv) Half the amount due to Paras is to be paid immediately.
Prepare Paras’s Capital Account and Paras’s Executor’s Account
On 1st April, 2022, Suvlan Ltd. issued 2,000, 8% Debentures of ₹ 100 each at a discount of 10%, redeemable at par after five years. The company has a balance of ₹ 1,70,000 in Securities Premium Account
(a) Record necessary journal entries for the issue of debentures
(b) Record necessary journal entries for writing off ‘Discount on Issue of Debentures’ utilising Securities Premium Account at the end of the first year itself
(c) Prepare ‘Discount on Issue of Debentures Account’ for the year ended 31st March, 2023.
Diamond Ltd. issued a prospectus inviting applications for 20,000 shares of ₹10 each. The amount was payable as follows:
On Application – ₹4 per share
On Allotment – ₹4 per share
On First and Final call – Balance
Applications for 45,000 shares were received and allotment was made as follows :
Category (i) – Applicants for 35,000 shares were allotted 15,000 shares.
Category (ii) – Applicants for 10,000 shares were allotted 5,000 shares.
It was decided that excess money received on application be adjusted towards sum due on allotment and calls.
Amar, an applicant of Category (ii), who was allotted 500 shares, failed to pay the first and final call. His shares were forfeited and subsequently reissued at ₹ 2 per share as fully paid up
Pass necessary journal entries to record the above transactions in the books of Diamond Ltd.
Pearl Ltd. issued a prospectus inviting applications for 40,000 shares of ₹ 10 each at a premium of 20%. The amount was payable as follows :
On Application – ₹ 5 per share
On Allotment – ₹ 5 per share (Including Premium)
On First and Final call – Balance
Applications for 60,000 shares were received and allotment was made on a pro-rata basis to all the applicants. Excess money received on application was adjusted towards the amount due on allotment.
Sameer who had applied for 1,200 shares failed to pay the allotment money. His shares were forfeited immediately after allotment. All the forfeited shares were reissued at ₹ 7 per share as ₹ 8 paid up. First and final call was not yet made.
Pass necessary journal entries to record the above transactions in the book of Pearl Ltd. Open ‘Calls in Arrears Account’ wherever necessary.
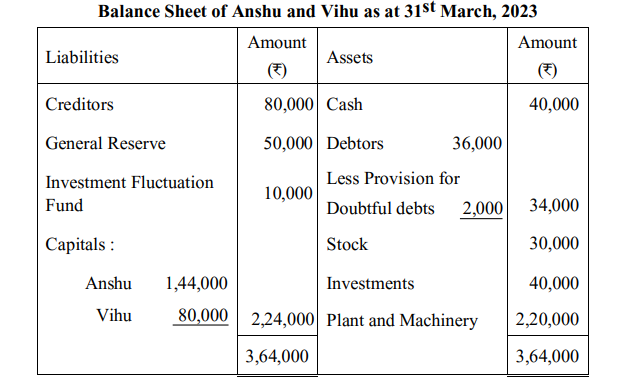
Anshu and Vihu were partners in a firm sharing profits and losses in the ratio of 3 :2. Their Balance Sheet as at 31st March, 2023 was as follows :
On 1st April, 2023, Mani was admitted into partnership for 1 / 5 th share in the profits of the firm on the following terms :
(i) Mani brought ₹ 20,000 as her share of goodwill and proportionate capital.
(ii) Provision for doubtful debts was to be maintained at 10% on debtors.
(iii) Market value of investments was ₹35,000.
(iv) The value of Plant and Machinery be increased by ₹6,600.
Prepare Revaluation Account and Partners’ Capital Accounts
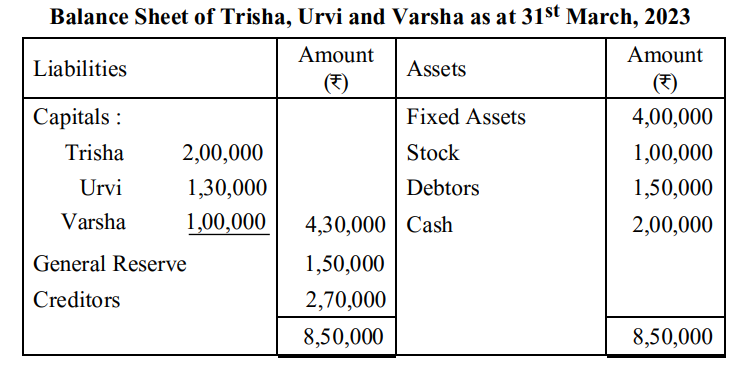
Trisha, Urvi and Varsha were partners in a firm sharing profits and losses in the ratio of 5 : 4 : 1. Their Balance Sheet as at 31st March, 2023 was as follows :
Trisha retired on 1st April, 2023 and the partners agreed to the following terms :
(i) Fixed Assets were found overvalued by ₹ 80,000.
(ii) Stock was taken over by Trisha at ₹80,000.
(iii) Goodwill of the firm was valued at ₹ 1,00,000 on Trisha’s retirement and Trisha’s share by goodwill was adjusted through the Capital Accounts of remaining partners.
(iv) New profit sharing ratio between the remaining partners was agreed at 2 : 3.
(v) Trisha was paid ₹50,000 on retirement and the balance was transferred to her loan account.
Pass necessary journal entries in the books of the firm on Trisha’s retirement.
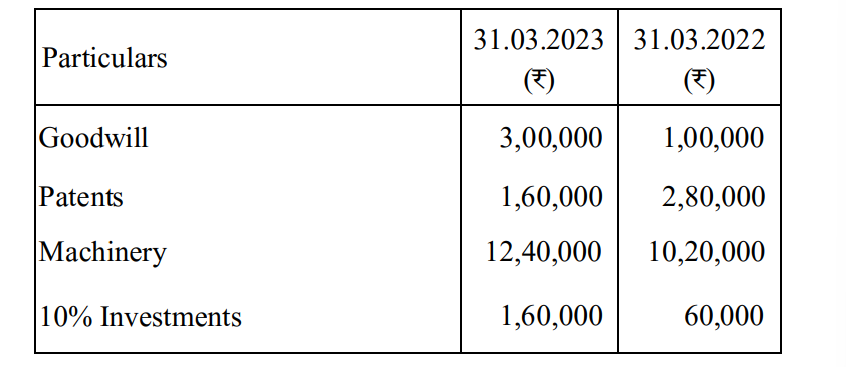
From the following particulars of Ruparel Ltd., calculate ‘Cash Flow from Investing Activities’. Show your working clearly.
Additional Information :
(i) Patents of ₹1,20,000 were sold at book value.
(ii) Depreciation charged during the year on machinery was ₹ 1,40,000. A machine having a book value of ₹ 80,000 was sold for ₹50,000
(iii) On 31.03.2023, 10% investments were purchased for ₹ 1,80,000 and some investments were sold at a profit of ₹ 20,000.
Interest received on investments was ₹ 6,000.
Paper Details
CBSE Board Exam 2024
Class
Class 12 Commerce
Subject
Accountancy
Year
2024
Set
Set 3
Other Years — Accountancy