QUESTION PAPER
2025 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2025 — Set 1
2025
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2025
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 46 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 27 are multiple choice questions
- Section B – questions number 28 to 35 are short answer
- Section C – questions number 36 to 39 are long answer type i
- Section D – questions number 40 to 46 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
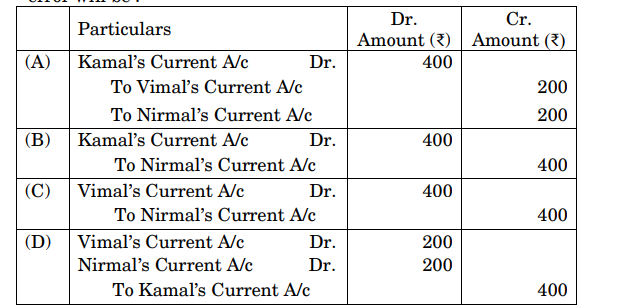
There are two statements, Assertion (A) and Reason (R)
Assertion (A) : Under the fluctuating capital method, only one account, i.e., capital account is maintained for each partner.
Reason (R) : All the adjustments such as share of profit and loss, interest on capital, drawings, interest on drawings, salary or commission to partners, etc. are recorded directly in the capital accounts of the partners
On 1st April, 2023, Saya Ltd. issued 7,000, 9% debentures of ₹ 100 each at a premium of 10%. The total amount of interest on debentures for the year ending 31st March, 2024 will be :
Ali and Bani were partners in a firm. They admitted Chaman as a new partner with 1 / 4 th share in the profits of the firm. Chaman brought ₹ 5,00,000 as his share of capital. The value of assets of the firm on Chaman’s admission was ₹ 20,00,000 and outside liabilities were ₹ 12,00,000. The goodwill of the firm on Chaman’s admission was :
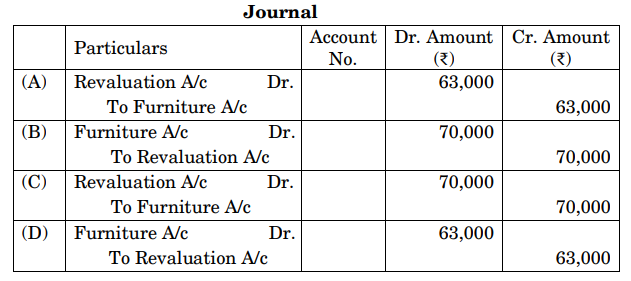
P and Q are partners in a firm sharing profits and losses equally. They admitted R into the partnership firm on 1st April, 2024. It was decided to value goodwill at 2 years’ purchase of super profits. The capital of the firm of P and Q was ₹ 5,00,000 and the normal rate of return on capital employed was 10%. During the year ended 31st March, 2024, the profit of the firm was ₹ 2,10,000. The value of goodwill of the firm was :
The debentures which are payable on the expiry of a specified period either in lump sum or in instalments during the lifetime of the company are known as ____________ debentures
Rima, Seema and Atul were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 1. With effect from 1st April, 2024, they decided to share profits and losses in the ratio of 3 : 1 : 4. Due to change in the profit sharing ratio, Seema’s gain or sacrifice will be:
Rohan, Piyush and Suman were partners in a firm sharing profits and losses in the ratio of 3 : 2 : 2. Piyush retired. The new profit sharing ratio between Rohan and Suman after Piyush’s retirement was 4 : 3. The gaining ratio of remaining partners will be :
Ranjeet and Ranvijay started a partnership firm on 1st April, 2023. According to the partnership deed, interest on drawings was to be charged @ 10% per annum. Ranjeet withdrew a fixed amount at the end of each month. The total yearly interest on Ranjeet’s drawings was ₹ 6,600. The amount of Ranjeet’s drawings for the year ended 31st March, 2024 was
On the dissolution of the partnership firm of Gauri and Gaurav, Building appeared in the books at ₹ 21,00,000. One-third of the Building was taken by Gaurav at 20% discount and the remaining was sold at 10% profit. The value at which the Building was taken over by Gaurav was :
Mathur, Jain and Verma were partners in a firm sharing profits and losses in the ratio of 3 : 2 : 1. Jain was guaranteed that his share of profit will not be less than ₹ 80,000. The firm’s profit for the year ended 31st March, 2024 was ₹ 1,80,000. The amount of deficiency borne by Verma was :
At the time of forfeiture of shares, Share Capital Account will be debited with :
Divya and Saurabh are partners in a firm. On 1st October, 2023, Saurabh advanced a loan of ₹ 5,00,000 to the firm. There is no partnership deed. On 31st March, 2024, Saurabh was entitled to get the following amount as interest on loan :
Manav and Adi were partners in a firm sharing profits and losses in the ratio of 5 : 3. Roy was admitted with 1 5 th share in the profits of the firm. At the time of Roy’s admission, Workmen’s Compensation Reserve appeared in the Balance Sheet of the firm at ₹ 4,00,000. The claim on account of workmen’s compensation was determined at ₹ 4,40,000. The excess amount of claim over the reserve will be debited to :
Anya and Sanya were partners in a firm sharing profits and losses in the ratio of 5 : 2. They admitted Vanya as a new partner for 3 / 7 7 th share in the profits of the firm. She acquired 2 / 7 th share from Anya and 1 / 7 th share from Sanya. The new profit sharing ratio of Anya, Sanya and Vanya will be :
Choose the correct equation with respect to capital employed from the following :
Statement I : Purchase of goodwill is classified as investing activity in case of all types of enterprises. Statement II :Payment of interest is classified as financing activity in case of all types of enterprises.
Manish Ltd. had balance in Provision for Taxation Account of ₹ 9,00,000 and ₹ 12,00,000 as on 31st March, 2023 and 2024 respectively. Provision for tax made during the year was ₹ 6,00,000. The amount of tax paid during the year was :
Acquisition of machinery by issue of equity shares of ₹ 30,00,000 will result in :
Section B
Pass necessary journal entries for the following transactions on the dissolution of the partnership firm of Banu, Bansal and Bimal after various assets (other than cash) and external liabilities have been transferred to Realisation Account :
(i) The firm had a balance of ₹ 4,80,000 in General Reserve on the date of dissolution.
(ii) Banu had given a loan of ₹ 80,000 to the firm which was fully settled at ₹ 78,000.
(iii) Realisation expenses of ₹ 17,000 were paid by Bansal.
From the following information, calculate the value of goodwill of the firm :
(i) On the basis of capitalisation of super profits, and
(ii) On the basis of capitalisation of average profits.
Average profit for the last four years − ₹ 20,00,000
Capital Employed − ₹ 25,00,000
Normal Rate of Return − 20%
Net Assets of the business − ₹ 25,00,000
A, B and C were partners in a firm sharing profits and losses in the ratio of 2 : 3 : 1. Goodwill appeared in their books at ₹ 3,00,000. B retired from the firm on 1st April, 2024. On that date, the goodwill of the firm was valued at ₹ 5,40,000.
Pass the necessary Journal entries in the books of the firm for the treatment of goodwill on B’s retirement.
Aman Ltd. took over the assets of ₹ 15,00,000 and liabilities of ₹ 17,00,000 of Kamini Ltd. for a purchase consideration of ₹ 30,00,000. Aman Ltd. paid 40% of the purchase consideration by cheque and the balance amount by issue of fully paid equity shares of ₹ 100 each at a premium of 50% in favour of Kamini Ltd. Pass necessary journal entries for the above transactions in the books of Aman Ltd
Astha Ltd. took over assets of ₹ 20,00,000 and took over liabilities of ₹ 1,00,000 of Nabha Ltd. for a purchase consideration of ₹ 18,00,000. Astha Ltd. paid half of the amount of purchase consideration through a bank draft and the balance amount was settled by issuing 12% Debentures of ₹ 100 each at a discount of 10% in favour of Nabha Ltd. Pass necessary journal entries for the above transactions in the books of Astha Ltd
Lalit, Madhur and Neel were partners in a firm sharing profits and losses in the ratio of 2 : 2 : 1. Neel retired and his capital after making the necessary adjustments on account of reserves and revaluation of assets and liabilities was ₹ 10,00,000. Lalit and Madhur agreed to pay Neel ₹ 22,00,000 in full settlement of his claim.
Pass necessary journal entries for the treatment of goodwill and making final payment to Neel
Name the major heads and sub-heads (if any) under which the following items will be shown in the Balance Sheet of a company as per Schedule III, Part I of the Companies Act, 2013
(i) Accrued Income
(ii) Work-in-progress
(iii) Capital Advances
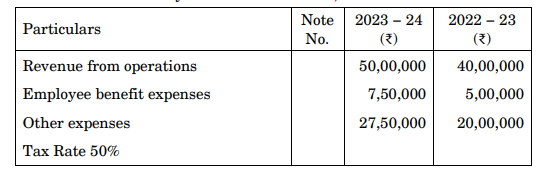
From the following information, prepare a Comparative Statement of Profit and Loss for the year ended 31st March, 2023 and 2024 :
Section C
Pass necessary journal entries for the issue of 11% Debentures in the books of Arpita Ltd. in the following cases :
(i) Issued 2,000, 11% Debentures of ₹ 100 each at a premium of 10%, redeemable at a premium of 5%.
(ii) Issued 5,000, 11% Debentures of ₹ 100 each at a discount of 10%, redeemable at a premium of 5%.
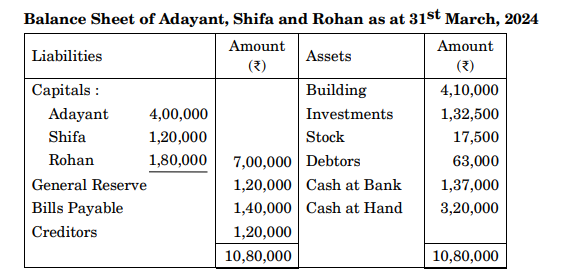
Adayant, Shifa and Rohan were partners in a firm sharing profits and losses in the ratio of 2 : 1 : 2. Their Balance Sheet as at 31st March, 2024 stood as follows :
Partners profit sharing ratio 2:1:2 - Profit and loss distribution based on ratio - Using balance sheet for capital adjustments and financial position
Shifa died on 30th June, 2024. As per the partnership deed, the executors of Shifa were entitled to :
(i) Amount standing to the credit of her capital account.
(ii) Interest on capital which was ₹ 5,750.
(iii) Her share of goodwill which was ₹ 42,000.
(iv) Her share in the profits of the firm from the date of the last Balance Sheet up to the date of death which amounted to ₹ 76,250.
(v) Shifa’s executors were paid half of the payable amount immediately and the balance amount was to be paid in two equal yearly instalments along with interest 8% p.a.
Pass necessary journal entries for the above transactions on Shifa’s death.
Calculate Current Assets and Quick Assets of a company from the following information :
Quick Ratio = 0·70 : 1
Inventory Turnover Ratio = 5 times
Inventory at the end was ₹ 20,000 more than inventory in the beginning
Gross Profit = ₹ 75,000
Current Liabilities = ₹ 80,000
Revenue from Operations = ₹ 4,00,000
Calculate ‘Return on Investment’ from the following information :
Net profit after interest and tax ₹ 6,00,000
10% Debentures ₹ 20,00,000
Capital employed ₹ 50,00,000
Tax rate 40%
Section D
Hira Ltd. invited applications for issuing 1,00,000 equity shares of ₹ 10 each at 10% premium. The amount was payable as follows :
On Application — ₹ 3 per share
On Allotment — ₹ 3 per share (including premium)
On first and final call — Balance amount
Applications were received for 1,40,000 shares and shares were allotted on a pro-rata basis to all the applicants. The excess money received on application was adjusted towards sums due on allotment. All the shareholders paid the allotment money due except one shareholder who was allotted 1,000 shares. These shares were forfeited immediately. All these shares were reissued to Shashi as ₹ 5 paid up for ₹ 4 per share. First and final call has not been made.
Pass necessary journal entries in the books of Hira Ltd. Open Calls-in-Arrears Account wherever required
Pass necessary journal entries for forfeiture and reissue of shares in the following cases :
(i) Krisha Ltd. forfeited 1,000 shares of ₹ 10 each, fully called-up on which only ₹ 4,000 had been received. 500 of the forfeited shares were reissued for ₹ 8 per share fully paid-up
(ii) XYZ Ltd. forfeited 20,000 shares of ₹ 10 each issued at a premium of ₹ 1 per share, for non-payment of second and final call of ₹ 2 per share. 70% of these shares were reissued at ₹ 7 per share fully paid-up.
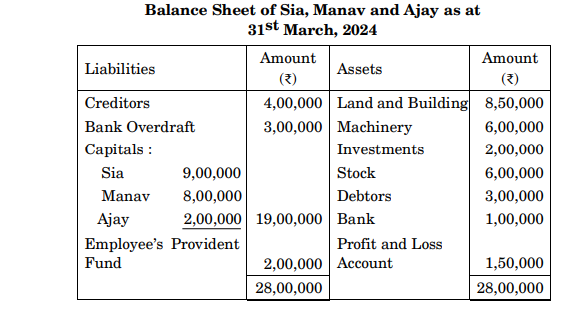
Sia, Manav and Ajay were partners in a firm sharing profits and losses in the ratio of 2 : 2 : 1. On 31st March, 2024, their Balance Sheet was as follows :
On 31st March, 2024, Manav retired from the firm and the remaining partners decided to carry on the business. The assets and liabilities were revalued which resulted into a gain of ₹ 1,20,000 because of the increase in the value of Land and Building by the same amount.
(i) 40% of Land and Building were taken by retiring partner at revalued value.
(ii) Goodwill of the firm be valued at ₹ 4,00,000. Sia and Ajay decided to share future profits and losses in the ratio of 3 : 2.
(iii) The total capital of the new firm will be ₹ 20,00,000 which will be in proportion of the new profit sharing ratio of Sia and Ajay. For this, necessary cash was brought in or was paid off to the partners, as the case may be. Prepare Partners’ Capital Accounts.
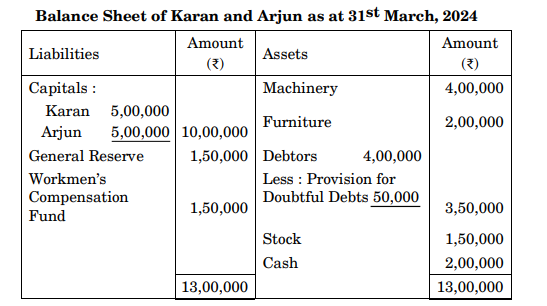
Karan and Arjun were partners in a firm sharing profits and losses in the ratio of 3 : 2. On 31st March, 2024, their Balance Sheet was as follows :
On 1st April, 2024, Nakul was admitted into the partnership for 1 / 4th share in the profits of the firm on the following terms :
(i) Nakul brought ₹ 4,00,000 as his capital and his share of goodwill premium in cash. Goodwill of the firm was valued at ₹ 2,00,000.
(ii) Furniture was valued at ₹ 2,50,000.
(iii) A provision for doubtful debts @ 10% is to be maintained on debtors
(iv) The liability against Workmen’s Compensation Fund was estimated at ₹ 1,20,000
(v) After the above adjustments, the capitals of Karan and Arjun were to be adjusted taking Nakul’s capital as the base. Excess or shortage in the capital accounts of Karan and Arjun was to be adjusted by opening current accounts.
Prepare Revaluation Account and Partners’ Capital Accounts.
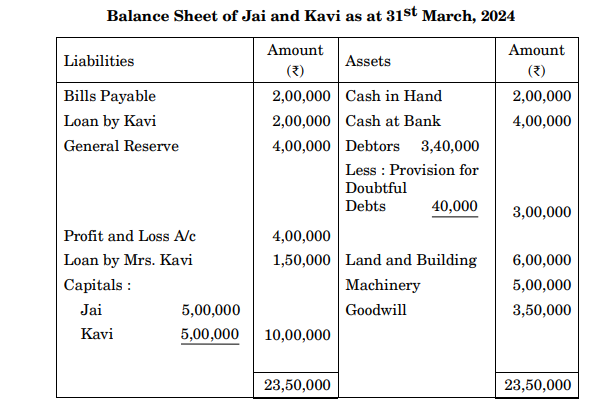
Jai and Kavi were partners in a firm sharing profits and losses equally. They agreed to dissolve the firm on 31st March, 2024. Their Balance Sheet as on 31st March, 2024 was as follows :
The following transaction took place at the time of dissolution :
(i) Land and Building realised ₹ 4,50,000.
(ii) Jai took Machinery at ₹ 4,50,000
(iii) Bills Payable were paid ₹ 1,96,000 in full settlement
(iv) Debtors realised at ₹ 2,70,000.
(v) Firm had to pay ₹ 5,000 for Outstanding Salary which was not provided earlier.
(vi) Realisation expenses were ₹ 19,000
Prepare Realisation Account.
Nisha Ltd. was registered with a capital of ₹ 6,00,000 in shares of ₹ 100 each. It issued 4,000 shares. The amount was payable as follows :
On Application — ₹ 30 per share
On Allotment — ₹ 30 per share
On First and Final Call — Balance
The issue was fully subscribed and all amounts payable on application and allotment were duly received. Amit, a shareholder, failed to pay first and final call of ₹ 40 per share on his 200 shares.
Answer the following questions :
(i) The Authorised capital of Nisha Ltd. shown in ‘Notes to Accounts’ will be :
(A) ₹ 6,00,000
(B) ₹ 4,00,000
(C) ₹ 6,00,00,000
(D) ₹ 3,60,000
(ii) The Issued capital of Nisha Ltd. shown in ‘Notes to Accounts’ will be :
(A) ₹ 3,60,000
(B) ₹ 6,00,000
(C) ₹ 4,00,000
(D) ₹ 3,92,000
(iii) ‘Subscribed and not fully paid up capital’ shown in ‘Notes to Accounts’ will be :
(A) ₹ 3,92,000
(B) ₹ 20,000
(C) ₹ 3,80,000
(D) ₹ 12,000
(iv) ‘Subscribed and fully paid capital’ of Nisha Ltd. shown in ‘Notes to Accounts’ will be :
(A) ₹ 20,000
(B) ₹ 3,80,000
(C) ₹ 12,000
(D) ₹ 3,92,000
(v) Calls in arrears of Nisha Ltd. will be :
(A) ₹ 12,000
(B) ₹ 20,000
(C) ₹ 8,000
(D) Nil
(vi) The amount of ‘Share Capital’ shown under ‘Shareholders’ Funds’ in the Balance Sheet of Nisha Ltd. will be
(A) ₹ 3,92,000
(B) ₹ 3,80,000
(C) ₹ 4,00,000
(D) ₹ 6,00,000
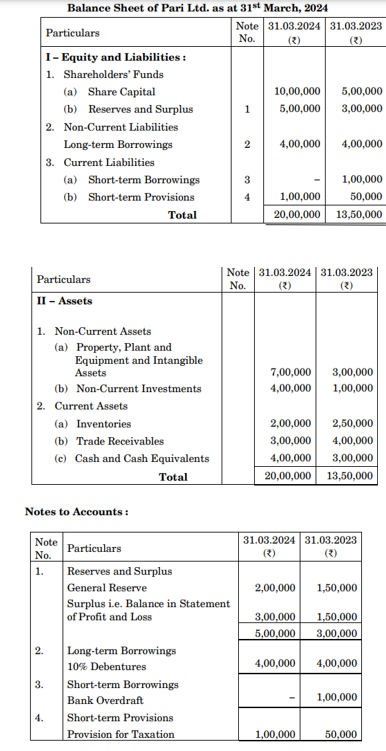
Calculate Cash Flows from Operating and Investing Activities on the basis of the information given in the Balance Sheet of Pari Ltd. as at 31st March, 2024.
Paper Details
CBSE Board Exam 2025
Class
Class 12 Commerce
Subject
Accountancy
Year
2025
Set
Set 1
Other Years — Accountancy