Class 12 Humanities . Economics . Introductory Macro Economics . Government Budget and the Economy
Chapter 5: Government Budget and the Economy
Ch 5
Economics
Class 12 Humanities
Introduction
Government in a Mixed Economy
- Mixed economy: An economy has both a private sector and a government sector.
- Government’s role: The government influences economic life and promotes people’s welfare through its functions and budget.
Meaning of the Government Budget
- Government budget: An annual statement of the government’s estimated receipts and expenditure.
- Constitutional requirement: Article 112 requires the government to present the Annual Financial Statement to Parliament for each financial year, from 1 April to 31 March.
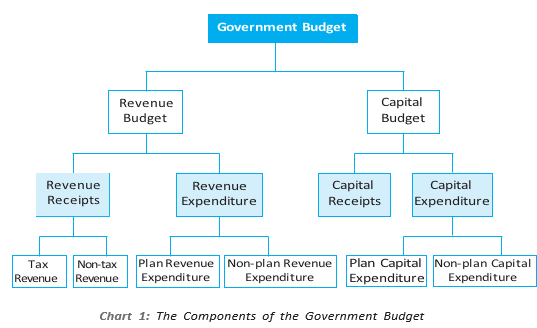
- Revenue budget: Records receipts and expenditure relating to the current financial year.
- Capital budget: Records transactions affecting the government’s assets and liabilities.
Quick recap
- A mixed economy includes both the private sector and the government.
- The government uses its budget to influence economic life.
- Article 112 requires India’s Annual Financial Statement to be presented to Parliament.
- India’s financial year runs from 1 April to 31 March.
- The revenue account covers current-year items; the capital account covers assets and liabilities.
- A budget’s effects may continue beyond the financial year it covers.
Objectives of Government Budget
Why the Government Uses the Budget
- Purpose: The government uses its budget to promote people’s welfare and influence the economy.
- Main functions: Allocation of resources, redistribution of income, and stabilisation of the economy.
Allocation Function
Allocation function — The government allocates resources to provide goods and services that the market may not provide adequately, especially public goods.
| Point | Private goods | Public goods |
|---|---|---|
| Rivalry | One person’s use reduces what is available to others. | One person’s use does not reduce the benefits available to others; consumption is non-rivalrous. |
| Exclusion | People who do not pay can generally be excluded. | It is difficult or impossible to exclude people, including those who do not pay. |
| Examples | Food, clothes, cars | National defence, roads, government administration, public parks, air-pollution control |
Why Public Goods Need Government Support
- Free riders: People may enjoy a public good without paying because excluding non-payers is difficult.
- Market limitation: Consumers have little incentive to pay voluntarily for benefits they can receive for free.
- Government role: The payment link between producer and consumer may break down, so the government arranges and finances public goods.
| Point | Public provision | Public production |
|---|---|---|
| Meaning | The good is financed through the government budget and can be used without direct payment. | The good is produced directly by the government. |
| Who produces? | Either the government or the private sector may produce it. | The government produces it. |
Redistribution Function
Redistribution function — The government uses taxes and transfers to influence household disposable incomes and achieve a distribution of income considered fair by society.
Income and Redistribution
- National income goes to the private sector (firms and households) or the government as public income.
- Private income that reaches households is personal income.
- After the relevant deductions, the amount households can spend is personal disposable income.
- Government taxes and transfers affect personal disposable income and can change how income is distributed.
Stabilisation Function
Stabilisation function — The government adjusts demand to reduce fluctuations in income, employment, and prices.
Aggregate Demand and Economic Fluctuations
- Aggregate demand: Employment and the general price level depend partly on total demand, shaped by government and private spending decisions.
- Demand shortfall: Demand may be too low to use all labour and other resources; wages and prices may not fall enough to restore employment automatically.
- Demand excess: When demand exceeds available output at high employment, it can cause inflation.
- Government response: It may expand demand to address a shortfall or restrict demand to curb excess and inflation.
Demand Shortfall and Government Response
- Insufficient aggregate demand
- Labour and other resources are not fully employed
- Wages and prices do not fall enough to restore employment automatically
- Government intervenes to increase aggregate demand
Excess Demand and Government Response
- Demand exceeds available output when employment is high
- Excess demand puts upward pressure on prices
- Inflation may result
- Government restricts demand to help reduce inflationary pressure
- Public good
- A good whose benefits are non-rivalrous and from which it is difficult or impossible to exclude non-payers.
- Free rider
- A person who receives the benefit of a good without paying for it.
- Personal disposable income
- The part of household personal income available for spending.
- Aggregate demand
- Total demand for goods and services in the economy.
How do public goods differ from private goods?
How does the government perform the redistribution function?
How does the budget help stabilise the economy?
Quick recap
- The government budget supports welfare through allocation, redistribution, and stabilisation.
- Public goods are non-rivalrous and difficult to exclude non-payers from; free riders may therefore arise.
- Public provision means budget financing; public production means direct production by the government.
- Taxes and transfers affect personal disposable income and help redistribute income.
- Low aggregate demand can leave resources unemployed; government may act to raise demand.
- Excess demand at high employment can cause inflation; government may restrict demand.
Classification of Receipts
Revenue Receipts
Revenue receipts — Government receipts that neither create a liability nor reduce its financial assets; they are non-redeemable.
| Type | Examples / Features |
|---|---|
| Tax revenue | Direct taxes and indirect taxes collected by the government. |
| Non-tax revenue | Interest receipts, dividends and profits, fees, service receipts, and cash grants-in-aid from foreign countries and international organisations. |
| Tax type | Examples / meaning |
|---|---|
| Direct taxes | Personal income tax and corporation tax on firms. |
| Indirect taxes | Excise duties on goods produced within the country; customs duties on goods imported into and exported out of India; service tax. |
| Other direct taxes | Wealth tax, gift tax and estate duty (now abolished); these raised little revenue and were called “paper taxes”. |
Tax Rates and Redistribution
- Progressive income tax: Higher income is taxed at a higher rate; this supports redistribution.
- Proportional corporation tax: Firms pay tax at a fixed proportion of their profits.
- Excise duties: Necessities are exempt or lightly taxed; comforts and semi-luxuries are moderately taxed; luxuries, tobacco and petroleum products are heavily taxed.
- Revenue estimates: They include the effects of tax proposals made in the Finance Bill.
| Point | Revenue receipts | Capital receipts |
|---|---|---|
| Effect | Do not create a government liability or reduce financial assets. | Create a liability or reduce the government's financial assets. |
| Examples | Taxes, fees, interest receipts and dividends. | Loans and sale of government assets, such as PSU disinvestment. |
| Future consequence | No repayment obligation or loss of an asset follows from the receipt itself. | Loans must be repaid with interest; a sold asset no longer provides future earnings. |
Capital receipts — Government receipts that either create liabilities or reduce its financial assets; they may be debt-creating or non-debt-creating.
| Type | Effect | Example |
|---|---|---|
| Debt-creating | Creates a liability; repayment and interest are due in future. | Fresh government loans. |
| Non-debt-creating | Reduces financial assets; future earnings from the asset are lost. | Sale of government shares in Public Sector Undertakings (PSUs), called PSU disinvestment. |
Classification of Expenditure
Revenue expenditure — Expenditure that does not create physical or financial assets of the central government.
Revenue Expenditure: What It Covers
- Normal operations: Running government departments and providing services.
- Other items: Interest payments on government debt and grants to state governments and other parties.
- Important: A grant is classified as revenue expenditure even if it is intended to help create an asset.
| Category | Coverage / examples |
|---|---|
| Plan expenditure | Central Plans (including Five-Year Plans) and central assistance for State and Union Territory plans. |
| Non-plan revenue expenditure | General, economic and social services; major items include interest payments, defence, subsidies, salaries and pensions. |
| Non-plan capital expenditure | Capital spending across the government's general, social and economic services. |
Important Non-Plan Revenue Items
- Interest payments: The single largest component; include interest on market loans, external loans and various reserve funds.
- Defence: Committed expenditure because national security leaves little scope for drastic cuts.
- Subsidies: A policy instrument to increase welfare; they may be implicit or explicit.
- Implicit subsidies: Public goods and services such as education and health are provided at under-priced rates.
- Explicit subsidies: Provided for items such as exports, interest on loans, food and fertilisers.
Capital expenditure — Expenditure that creates physical or financial assets, or reduces financial liabilities.
Capital Expenditure: Examples
- Asset creation: Acquisition of land, buildings, machinery and equipment, and investment in shares.
- Loans and advances: Lending by the central government to State and Union Territory governments, PSUs and other parties.
- Plan capital expenditure: Central Plans and central assistance for State and Union Territory plans.
- Non-plan capital expenditure: Capital spending relating to the government's general, social and economic services.
Subsidies as a Share of GDP
- 2014–15Subsidies were 2.02% of GDP.
- 2015–16Subsidies were 1.8% of GDP.
- 2018–19Subsidies were 1% of GDP.
- 2020–21Subsidies were 3.6% of GDP.
- 2022–23 (B.E.)Subsidies were estimated at 1.2% of GDP.
The Budget and Fiscal Policy Statements
The Budget as a Policy Statement
- Beyond accounts: The budget is not only a statement of receipts and expenditure; it is also a national policy statement.
- Economic relationship: The budget reflects and shapes the country's economic life, while economic conditions also influence the budget.
- Planning context: Since Independence, the introduction of Five-Year Plans has made the budget an important instrument of national policy.
Fiscal Responsibility and Budget Management Act
- 2003The FRBMA mandated three policy statements to accompany the budget.
| Statement | Main purpose |
|---|---|
| Medium-term Fiscal Policy Statement | Sets three-year rolling targets for specific fiscal indicators; assesses whether revenue expenditure can be sustainably financed by revenue receipts and whether capital receipts, including market borrowings, are used productively. |
| Fiscal Policy Strategy Statement | Sets government priorities in fiscal policy, reviews current policies and explains deviations in important fiscal measures. |
| Macroeconomic Framework Statement | Assesses economic prospects, including GDP growth, the central government's fiscal balance and the external balance. |
- PSU disinvestment
- Sale of government shares in Public Sector Undertakings; it is a non-debt-creating capital receipt.
- Committed expenditure
- Spending, such as defence expenditure, that has little scope for drastic reduction.
- B.E.
- Budget Estimate.
- FRBMA
- Fiscal Responsibility and Budget Management Act, 2003.
How do revenue receipts differ from capital receipts?
Distinguish revenue expenditure from capital expenditure.
Name the three fiscal policy statements mandated by the FRBMA, 2003.
Quick recap
- Revenue receipts create no liabilities and do not reduce financial assets; they comprise tax and non-tax revenue.
- Capital receipts create liabilities or reduce financial assets; loans are debt-creating, while PSU disinvestment is non-debt-creating.
- Revenue expenditure does not create assets; capital expenditure creates assets or reduces financial liabilities.
- The budget classifies expenditure as plan and non-plan; major non-plan revenue items include interest, defence, subsidies, salaries and pensions.
- Subsidies can be implicit or explicit and are used as a welfare policy instrument.
- The FRBMA, 2003 requires three fiscal policy statements covering medium-term targets, fiscal strategy and macroeconomic prospects.
Balanced, Surplus And Deficit Budget
Balanced, Surplus and Deficit Budgets
- Budget balance: A budget is balanced when government expenditure equals revenue collected.
- Surplus budget: Revenue exceeds expenditure; a deficit budget occurs when expenditure exceeds revenue.
Measures of Government Deficit
- Deficit measures: Different measures show the extent and nature of the gap between government expenditure and receipts.
- Purpose: They help assess the government’s borrowing needs and the implications of its fiscal position for the economy.
Revenue Deficit
A positive value indicates that revenue expenditure exceeds revenue receipts.
Fiscal Deficit
Here, is total expenditure, is revenue receipts and is non-debt-creating capital receipts.
Net borrowing at home includes direct public borrowing and borrowing through commercial banks; the other sources are borrowing from the RBI and abroad.
A large revenue-deficit share of fiscal deficit signals that much borrowing supports consumption rather than investment.
Primary Deficit
is gross fiscal deficit and is net interest liabilities.
Fiscal Policy and Aggregate Demand
Taxes, Transfers and Equilibrium Income
is income, is lump-sum tax and is transfers.
is autonomous consumption; is the propensity to consume.
is investment and is government purchases.
Equilibrium requires output or income to equal aggregate demand.
Higher transfers, investment or government purchases raise equilibrium income; higher taxes lower it.
Changes in Government Expenditure
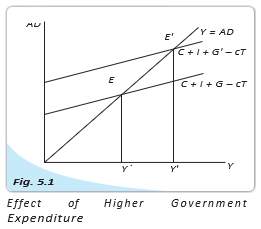
The multiplier gives the change in equilibrium income per unit change in government expenditure.
Changes in Taxes
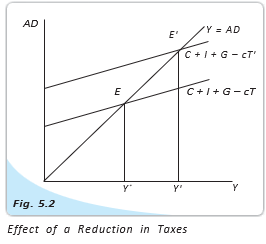
A tax change first changes consumption by , then affects income through the multiplier process.
The negative sign shows that taxes and equilibrium income move in opposite directions.
How do fiscal deficit and primary deficit differ?
Why can a revenue deficit harm growth and welfare?
Why is the tax multiplier smaller in absolute value than the government spending multiplier?
Quick recap
- A balanced budget has expenditure equal to revenue; a surplus has receipts above expenditure; a deficit has expenditure above receipts.
- Revenue deficit equals revenue expenditure minus revenue receipts and signals a shortfall in current government transactions.
- Fiscal deficit measures total borrowing needs; loan recoveries and PSU disinvestment proceeds are non-debt-creating capital receipts.
- Primary deficit equals fiscal deficit minus net interest liabilities, excluding interest obligations on accumulated debt.
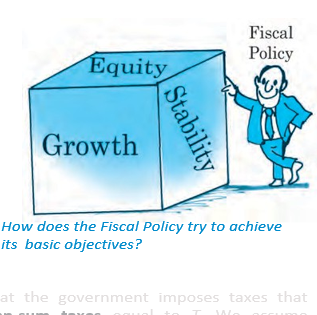
- Fiscal policy uses expenditure and taxes to influence output, income and employment; its objectives include growth, equity and stability.
- Government purchases affect aggregate demand directly; taxes and transfers affect it through disposable income and consumption.
- The spending multiplier is ; the tax multiplier is and is smaller in absolute value.
Examples of Balanced, Surplus And Deficit Budget
Government Spending and Tax Multipliers
Lump-sum taxes: Example 1
- Government expenditure multiplier measures the change in equilibrium income caused by a change in government spending.
- Tax multiplier measures the change in equilibrium income caused by a change in taxes; it is negative because higher taxes reduce disposable income and consumption.
- Given marginal propensity to consume, : government spending multiplier is , while the tax multiplier is .
- Example A 500; a 400.
- Comparison For lump-sum taxes, the tax multiplier is one less in absolute value than the government spending multiplier.
Use for changes in government spending or lump-sum taxes.
Balanced Budget Multiplier
Balanced budget multiplier — The change in equilibrium income when government spending and taxes rise by equal amounts; in this model, its value is one.
When the increase in government spending equals the increase in taxes, income rises by the amount of the spending increase.
Why the multiplier equals one
- Spending effect Government purchases directly add to income, then generate further rounds of consumption spending.
- Tax effect A tax rise reduces disposable income; consumption falls by times the tax increase, followed by further rounds of reduced spending.
- Net effect If spending and taxes rise equally, the initial direct increase in spending exceeds the first-round consumption reduction by exactly the spending increase.
- Example A 500 to income; a 400, leaving a net rise of 100.
- Equilibrium income This is the final income level after all rounds of the multiplier process have taken place.
Proportional Taxes
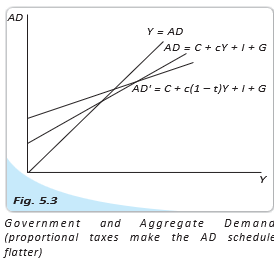
Proportional income tax — A tax collected as a constant fraction of income, so total tax is given by .
Income and the multiplier
- Slope of consumption With proportional taxes, consumption rises by for each extra unit of income, less than the rise with lump-sum taxes.
- Autonomous expenditure .
- Equilibrium Product-market equilibrium requires income to equal aggregate demand.
- Effect Because the consumption schedule is flatter, the multiplier is smaller than with lump-sum taxes.
Example 2
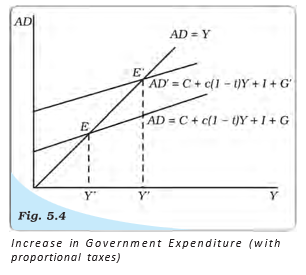
- Given and tax rate , the effective propensity to consume out of income is .
- Multiplier , lower than the lump-sum-tax multiplier of .
- Result A 250, rather than 500.
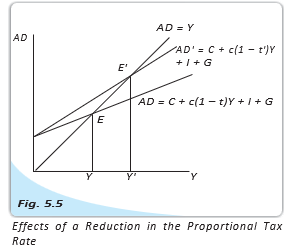
Tax-rate changes
- Tax reduction A lower proportional tax rate increases disposable income and consumption, shifting aggregate demand upward.
- Equilibrium effect At the original income level, demand exceeds output; income rises until a new equilibrium is reached.
Automatic and Discretionary Stabilisation
Automatic stabiliser — A feature of the fiscal system that automatically reduces economic fluctuations without a new policy decision.
How proportional taxes stabilise the economy
- Boom: GDP and income rise → tax payments rise → disposable income increases by less than GDP → consumption growth is restrained.
- Recession: GDP and income fall → tax payments fall → disposable income falls by less than GDP → consumption and aggregate demand are supported.
Discretionary fiscal policy — Deliberate changes in government spending or taxes to offset undesirable economic changes.
Stabilisation examples
- Offsetting lower investment If investment falls from to , raising government spending from to can maintain autonomous expenditure and equilibrium income.
- Welfare transfers Transfers support consumption during slumps; higher tax receipts during booms help restrain high consumption.
- Private built-in stabilisers Corporations may maintain dividends in the short run, while households try to maintain previous living standards.
- Limit Automatic stabilisers reduce only part of fluctuations; deliberate policy may be needed to address the rest.
Transfer Payments
Transfer multiplier with lump-sum taxes
- Transfers Unlike government purchases of goods and services, transfer payments are not direct additions to aggregate demand.
- Consumption channel Recipients consume only a fraction of an additional transfer; the rest is saved.
- Result The transfer multiplier is smaller than the government expenditure multiplier.
Use for a change in transfer payments under the lump-sum tax model.
Example 3
- Given and lump-sum taxes, the government expenditure multiplier is .
- Government purchases A 4(20)=80.
- Transfers A [0.75/(1-0.75)](20)=3(20)=60.
- Conclusion The same-sized rise in government purchases increases income more than a rise in transfers.
Why is the balanced budget multiplier equal to one?
How does a proportional income tax act as an automatic stabiliser?
Compare the effects of a c=0.75.
Quick recap
- Lump-sum tax multipliers: and .
- Balanced budget: Equal rises in government spending and taxes produce a multiplier of one.
- Proportional taxes: They lower the effective propensity to consume to and reduce the multiplier.
- Automatic stabilisers: Proportional taxes and welfare transfers moderate booms and recessions without a new decision.
- Discretionary policy: Deliberate fiscal changes can offset shifts such as a fall in investment.
- Transfers: Their multiplier is , so they raise income less than an equal increase in government purchases.
Debt
Government Debt and Deficits
Government debt — The accumulated amount the government owes, mainly because it has borrowed to finance budgetary deficits.
How deficits add to debt
- Deficit is a flow: it adds to the stock of government debt.
- Financing options are taxation, borrowing, or printing money; governments have generally relied on borrowing.
- Accumulation: repeated borrowing increases debt and the interest payable; interest payments can themselves add to debt.
Deficit-to-debt chain
- Budget deficit -> government borrowing
- Borrowing year after year -> rising debt stock
- Rising debt -> more interest payments -> possible further debt
Is Government Debt a Burden?
- Assess the whole economy: a government's debt is not identical to one trader's debt; governments can raise resources through taxation and printing money.
- Future-generation burden: bonds may be issued to people today, while repayment through future taxes reduces the disposable income and consumption of later taxpayers.
- Possible effect: lower national savings can reduce the funds available for private investment, capital formation and economic growth.
Traditional View and Ricardian Equivalence
| Point | Traditional view | Ricardian equivalence |
|---|---|---|
| Response to a tax cut and deficit | Consumers spend more of their higher after-tax income. | Forward-looking consumers save more, anticipating future taxes to repay borrowing. |
| View of future taxes | Consumers may overlook future taxes or expect them to fall on later generations. | Consumers consider future taxes and care about descendants as part of the family decision-making unit. |
| Effect on national saving | More consumption can reduce national saving. | Higher private saving offsets the government's borrowing, leaving national saving unchanged. |
| Financing implication | Borrowing can shift the burden to future taxpayers. | Taxation now and borrowing now are equivalent ways to finance spending, if future taxes are anticipated. |
Ricardian equivalence — The view that people anticipate future taxes from government borrowing and increase saving enough to offset the resulting change in government spending.
- Name: the idea is associated with David Ricardo, who argued that people save more when deficits are high.
- Equivalence: under this view, borrowing today and raising taxes later has the same effect as raising taxes today to finance the same government spending.
Who Owes the Debt?
| Point | Domestic debt | Foreign debt |
|---|---|---|
| Who receives payment | Resources move between people or generations within the nation; purchasing power remains in the country. | Interest payments go abroad and require the country to send goods overseas. |
| Burden | May redistribute resources within the country rather than remove purchasing power from it. | Involves a burden on the country through the transfer of goods abroad. |
Other Effects of Deficits and Debt
When a Deficit May Cause Inflation
- Higher government spending or lower taxes
- Aggregate demand rises
- If firms cannot increase output at current prices, demand exceeds supply
- Prices rise: the deficit is inflationary
When deficits need not be inflationary
- Unutilised resources: if output is held back by insufficient demand, deficit spending can raise demand and output without necessarily raising prices.
Crowding Out and Its Qualification
- Government issues bonds to borrow from private citizens
- Government bonds compete with corporate bonds and other financial instruments for funds
- Private borrowers may receive less funding, reducing private investment: this is called crowding out
- If deficit spending raises production and income, savings can also rise
- Higher savings may let both government and industry borrow more
Debt-Financed Public Investment
- Infrastructure: borrowing to invest can benefit future generations if the investment's return exceeds the interest rate.
- Debt repayment: growth in output may generate enough resources to pay off the debt.
- Assessment: judge debt growth against growth of the economy as a whole; debt is not automatically burdensome.
Reducing the Government Deficit
- Main options: increase taxes or reduce government expenditure.
- Tax revenue in India: policy has placed greater reliance on direct taxes; indirect taxes are regressive because they affect income groups alike.
- Other receipts: selling shares in public sector undertakings (PSUs) can raise government revenue.
- Efficiency: better programme planning and administration can reduce expenditure while improving government operations.
- Cash transfers: a Planning Commission study estimated that transferring Re. 1 to the poor through food subsidy cost Rs. 3.65; cash transfers could increase welfare.
- Spending priorities: cutting programmes in agriculture, education, health or poverty alleviation can harm the economy.
- Spending limits: some governments impose self-set constraints that cap expenditure at predetermined levels.
A larger deficit does not always mean a more expansionary fiscal policy: the same fiscal measures can produce different deficits as economic conditions change.
Why the Deficit Changes Over the Business Cycle
- Recession -> GDP and incomes fall
- Lower incomes -> households and firms pay less tax
- Tax revenue falls -> the deficit rises, even without a policy change
- In a boom, higher incomes and tax payments can reduce the deficit
- Government debt
- The accumulated stock of government borrowing.
- Ricardian equivalence
- The idea that anticipated future taxes lead consumers to save more, offsetting government borrowing.
- Crowding out
- Reduced private borrowing or investment when government borrowing competes for available funds.
How can government borrowing burden future generations?
What is Ricardian equivalence?
Explain crowding out and one qualification to it.
Quick recap
- Deficits are flows that add to the stock of government debt; borrowing also creates interest payments.
- Debt may burden future generations through future taxes and reduced private investment, but its effects depend on who owes and who receives payment.
- Ricardian equivalence says people may save more in anticipation of future taxes, offsetting government borrowing.
- Deficits can cause inflation when demand exceeds productive capacity, but may raise output when resources are idle.
- Government borrowing can crowd out private investment, though rising output and savings may soften this effect.
- Deficits can be reduced through higher taxes or lower spending, but cuts to vital programmes may harm the economy.
- A deficit may rise in recession and fall in a boom even when fiscal policy does not change.
Box
Fiscal Responsibility and Budget Management Act (FRBMA)
FRBMA — The Fiscal Responsibility and Budget Management Act is a rules-based framework requiring the central government to follow prudent fiscal policy and control deficits and borrowing.
Purpose and fiscal targets
- Purpose: Promote inter-generational equity and long-term macroeconomic stability through adequate revenue surplus, effective debt management and fewer fiscal obstacles to monetary policy.
- Fiscal deficit target: Reduce it to no more than 3% of GDP by March 31, 2009.
- Revenue deficit target: Eliminate it by March 31, 2009, and build an adequate revenue surplus thereafter.
- Annual reduction: Reduce fiscal deficit by 0.3 percentage points of GDP and revenue deficit by 0.5 percentage points each year.
- Adjustment: If tax revenue is insufficient to meet the targets, the government must make the necessary adjustment by reducing expenditure.
Other provisions
- Exceptions: Deficits may exceed targets only for national security, natural calamities or other exceptional grounds specified by the central government.
- RBI borrowing: The central government cannot borrow from the RBI, except through advances to meet temporary excess of cash disbursements over receipts.
- RBI and securities: From 2006–07, the RBI must not subscribe to primary issues of central government securities.
- Transparency: The Act requires measures to make fiscal operations more transparent.
- Parliamentary statements: Along with the Annual Financial Statement, the government must present the Medium-term Fiscal Policy Statement, Fiscal Policy Strategy Statement and Macroeconomic Framework Statement to both Houses.
- Quarterly review: Trends in receipts and expenditure relative to the budget must be reported to both Houses of Parliament every quarter.
Scope and review
- Coverage: The Act applies to the central government; 26 states have also enacted fiscal responsibility laws, broadening rules-based fiscal reform.
- Concern: Meeting deficit targets could lead to reductions in welfare expenditure.
- Review Committee: The FRBM Review Committee was assigned to retain the basic framework while updating it for India’s changing conditions and future growth needs.
- Changing outlook: Although fiscal rules were initially favoured over discretion, advanced economies later moved away from that approach; India continued to support the FRBM’s fiscal policy principles.
FRBMA milestones
- August 2003FRBMA was enacted, establishing a framework for prudent fiscal policy.
- July 2004Rules under the Act came into effect.
- March 31, 2009The Act set the deadlines to limit fiscal deficit to 3% of GDP and eliminate revenue deficit.
Goods and Services Tax (GST)
Goods and Services Tax (GST) — GST is a comprehensive indirect tax on the supply of goods and services, levied as they move through the supply chain to the consumer.
Core features
- Destination-based: GST is a consumption tax whose revenue is associated with the place of consumption.
- Input Tax Credit (ITC): Tax paid at an earlier supply stage can be credited against tax due at the next stage.
- Value-added tax: Tax is effectively charged on value added at each stage, rather than repeatedly on the full value including earlier taxes.
- Common market: GST applies across the country, with a common rate for each type of good or service.
- Tax consolidation: It combined many central and state/UT taxes and cesses on production, sales and services.
| Point | Pre-GST taxation | GST |
|---|---|---|
| Tax base | Taxes could be imposed on the full value, including taxes on intermediate goods and services. | Tax is effectively imposed on value added at each supply stage. |
| Tax credit | Input Tax Credit was limited, contributing to cascading taxation. | Credit for tax paid at the previous stage can be set off at the next stage. |
| Tax structure | Multiple central and state taxes and cesses applied. | Many of these taxes were brought under a unified system with standardised laws, procedures and rates. |
| Level of government | Examples of taxes and cesses |
|---|---|
| Central | Central Excise Duty, Service Tax, Central Sales Tax, and cesses such as KKC and SBC. |
| State/UT | VAT/Sales Tax, Entry Tax, Luxury Tax, Octroi, Entertainment Tax, taxes on advertisements, lottery/betting/gambling taxes, and state cesses on goods. |
| Category | Treatment |
|---|---|
| Standard GST rates | 0%, 3%, 5%, 12%, 18% and 28%. |
| Five petroleum products | Kept outside GST for the time being; intended to be brought under GST later. |
| Alcoholic liquor for human consumption | State Governments continue to levy VAT. |
| Tobacco and tobacco products | Subject to both GST and Central Excise Duty. |
Constitutional basis and benefits
- Constitutional authority: The 101st Constitution Amendment Act introduced Article 246A, empowering Parliament and state legislatures to make GST laws.
- Enabling laws: The CGST Act, UTGST Act and SGST Acts provided the legal framework for GST.
- Common market: Standardised tax rules facilitate the movement of goods and services across the country.
- Lower costs: GST aims to reduce tax cascading, business operating costs and overall production costs, supporting the competitiveness of Indian goods and services.
- Growth potential: The text states that GDP is expected to rise by about 2% as a result of GST.
- Administration: Online registration, returns and payments through a common portal make compliance easier and reduce direct taxpayer–government interaction.
- Other gains: GST expands the tax base, improves transparency and supports ease of doing business.
GST milestones
- September 8, 2016The President of India assented to the 101st Constitution Amendment Act.
- Midnight of June 30–July 1, 2017GST was launched during a special midnight session of Parliament.
- July 1, 2017GST became operational.
- Fiscal deficit
- The deficit measure that FRBMA targets at no more than 3% of GDP.
- Revenue deficit
- The deficit the Act aimed to eliminate and replace with a revenue surplus.
- Input Tax Credit (ITC)
- Credit for tax paid at an earlier stage of the supply chain, set off against tax due at a later stage.
- Cascading of tax
- Tax-on-tax that occurs when earlier taxes are included in the value taxed at later stages.
Quick recap
- FRBMA: Enacted in 2003, it set rules to limit deficits, manage borrowing and promote fiscal prudence.
- FRBMA targets: Fiscal deficit was to fall to at most 3% of GDP and revenue deficit to be eliminated by March 31, 2009.
- FRBMA accountability: The Act requires fiscal statements, quarterly reviews and greater transparency, with limited exceptions to deficit targets.
- GST: Introduced nationwide in 2017, it is a destination-based tax on goods and services with Input Tax Credit.
- GST effect: ITC reduces cascading by allowing tax paid at one supply stage to be credited at the next.
- GST scope: It replaced many central and state taxes, while specified petroleum products and alcoholic liquor remain outside the GST system for now.
Summary & Key Concepts
Public Goods
- Public goods: Goods and services whose benefits are available to the community, such as national defence, roads and public parks.
- Non-rivalrous: One person’s use does not reduce the amount or benefit available to others.
- Non-excludable: It is not feasible to prevent people from enjoying the benefits, even if they do not pay.
- Free riders: People may benefit without paying, making private provision difficult; therefore, the government provides public goods.
- Public provision: The government finances a good through the budget for use without direct payment; production may be by the government or private sector.
Quick recap
- Public goods are non-rivalrous and non-excludable, so government provision is generally needed.
- Government performs allocation, redistribution and stabilisation through its receipts and expenditure.
- The budget separates revenue and capital items to distinguish current needs from investment in capital stock.
- A rising revenue-deficit share of fiscal deficit can signal lower capital formation and poorer expenditure quality.
- Proportional taxes reduce the autonomous expenditure multiplier by lowering the marginal propensity to consume.
- Public debt is burdensome when it reduces future output growth.
Economics — ALL CHAPTERS
1
Indian Economy On The Eve Of Independence
2
Indian Economy 1950–1990
3
Liberalisation, Privatisation And Globalisation: An Appraisal
4
Human Capital Formation In India
5
Rural Development
6
Employment : Growth, Informalisation And Other Issues
7
Environment and Sustainable Development
8
Comparative Development Experiences of India And Its Neighbours
1
Introduction
2
National Income Accounting
3
Money and Banking
4
Determination of Income and Employment
5
Government Budget and the Economy
6
Open Economy Macroeconomics